Support at Home, Explained for Families: What Replaced Home Care Packages
On 1 November 2025, Home Care Packages became Support at Home — new name, eight levels instead of four, and money that now arrives in quarterly budgets. Nearly a year on from that change, plenty of families are still searching for the old Home Care Package name, so this guide keeps both names side by side. If you're helping Mum or Dad, this is the plain-English version, checked against the official sources.
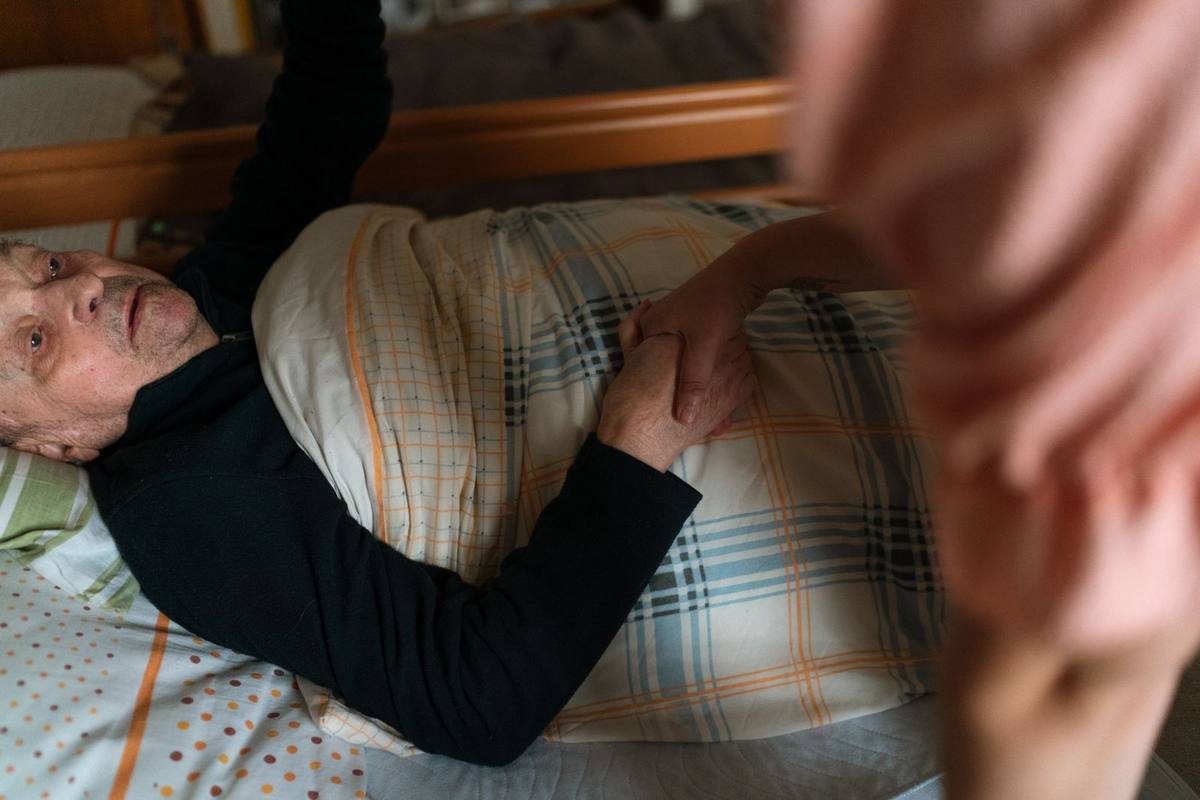
If your family is anything like the ones we hear from, it went something like this. Mum had a Home Care Package — Level 2, she'd finally come off the waiting list, a provider came twice a week — and then a letter arrived saying the program had a new name, her funding had moved across, and the rules for what she pays had changed. The letter was written for the system, not for her. And not for you, reading it over her shoulder at the kitchen table, trying to work out whether anything important had just been taken away.
Nothing was taken away. But plenty changed, and the official explanations assume you already speak fluent aged care. This guide is our translation. We read the My Aged Care and Department of Health pages line by line, pulled out every number that matters, and put it in the order a family actually needs it: what changed, what the money looks like now, what you'll pay, and the handful of steps worth taking this month. Where a number appears, it comes from the official schedule — and where the honest answer is "it depends on your parent's situation", we say so, and we tell you exactly who can confirm it for you.
The one sentence worth remembering from this whole page: Support at Home did not change who helps your parents — it changed how you ask, how you are assessed, and how the money follows them. The same cleaners, nurses and gardeners still turn up. What moved is the machinery behind them, and the machinery is now your family's job to steer.
Home Care Packages vs Support at Home: the side-by-side
The two systems fund the same kinds of help at home, but the structure is genuinely different. If you only read one table on this page, make it this one — it's the whole reform on a single screen.
| Home Care Packages (old — ended 1 Nov 2025) | Support at Home (current) | |
|---|---|---|
| Levels | 4 package levels (Level 1 to Level 4) | 8 funding classifications (Classification 1 to 8) |
| How the money arrives | An annual package amount, drawn down as services are used; unspent funds built up in the package | A quarterly budget, refreshed every three months; only a limited amount carries over |
| What you pay | A basic daily fee plus a possible income-tested care fee, set under the old rules | A percentage of each service you receive: 0% for clinical care, a set percentage for independence and everyday living services |
| Care management | Providers charged package management and care management fees from your package | 10% of your quarterly budget is set aside for care management — it's built into the published classification amounts |
| Equipment & home changes | Bought out of package funds — one big purchase could drain the package | A separate scheme (AT-HM) with its own funding tiers, so a ramp or shower chair doesn't eat the care budget |
| Short bursts of help | A separate program (Short-Term Restorative Care) with its own doorway | Built in as pathways: a Restorative Care Pathway and an End-of-Life Pathway |
| Your old package | — | Moved across automatically at an equivalent funding level, with your unspent funds kept |
Two of those rows deserve a second look, because they're where families most often get confused. The first is the quarterly budget. Under the old packages, money you didn't spend quietly accumulated — some families discovered tens of thousands of unspent dollars sitting in a package. Under Support at Home, the budget is deliberately smaller and faster-moving: it refreshes every quarter, and only a limited carryover (we'll give you the exact rule below) rolls forward. The system now expects the money to be spent on care as it arrives, not banked.
The second is what you pay. The old basic daily fee and income-tested care fee are gone for people in Support at Home. In their place is a cleaner — if less familiar — idea: every service belongs to one of three categories, and your contribution is a percentage of that service's price. Nursing costs you nothing. Help with showering costs a small percentage. Cleaning and gardening cost the largest percentage. We'll work through real examples in the payments section below.
What is Support at Home, in plain English?
Support at Home is the Australian Government's program for funding help that lets older people keep living safely in their own homes. It started on 1 November 2025 under the new Aged Care Act, replacing Home Care Packages and Short-Term Restorative Care. One doorway — My Aged Care — handles applications and assessments, and the money follows the person, not the provider.
Here's the shape of it. Your parent applies through My Aged Care and has an assessment at home. That assessment does two things: it decides which services they're approved for, and it places them in one of eight funding classifications matched to their needs. They then choose a registered provider, agree a care plan and a set of prices, and services begin — paid from a quarterly budget. The government pays the provider the bulk of each bill; your parent pays a set contribution toward non-clinical services, worked out from their income and assets.
Who is it for? Broadly, people aged 65 or over — 50 or over for Aboriginal and Torres Strait Islander people — who need help with daily life to stay at home: showering safely, keeping the house clean, getting to appointments, managing meals, recovering strength after a hospital stay. Eligibility is based on care needs, not money. A self-funded retiree and a full pensioner go through the same assessment door; money only changes what each of them contributes toward non-clinical services, not whether they're allowed in.
One boundary worth drawing clearly, because families mix these up: Support at Home is for help at home. It isn't residential aged care (a nursing home), and it isn't the entry-level Commonwealth Home Support Programme, which still runs separately — there's a section on that below, because plenty of parents receive that lighter help and their letters confused everyone.
The three kinds of help — and why the labels matter
Every service in Support at Home sits in one of three categories: clinical supports, independence supports, and everyday living supports. The category isn't paperwork — it decides what your parent pays toward that service, so it's worth knowing which help falls where before you look at any price list.
Clinical supports — best for health needs, and always fully funded. This is the care a health professional delivers or oversees: nursing care, wound care, medication support, and allied health such as physiotherapy, occupational therapy, podiatry, dietetics and speech pathology. The government pays 100% of clinical supports for everyone, whatever their income or assets. If your parent needs a nurse to dress a leg ulcer twice a week, that comes at no contribution from them. This is the single most generous rule in the new system, and many families don't realise it exists — if a provider's invoice ever shows your parent being charged a contribution toward nursing, that's a conversation to have immediately.
Independence supports — best for staying capable and safe day to day. This is the help that keeps someone functioning in their own home: personal care such as showering and dressing support, help getting to and from appointments, social support and community connection, respite so a carer can rest, and therapeutic services that support daily living. Contributions here are moderate — 5% for a full pensioner, rising with means to 50% for a self-funded retiree without a Commonwealth Seniors Health Card. Think of this category as the "keep Mum independent" bucket, and the contribution as the system's way of sharing a cost it mostly still carries.
Everyday living supports — best for the running of the house, with the highest contributions. Cleaning, laundry, meal preparation, gardening, shopping help and home maintenance live here. These services attract the largest contributions: 17.5% for a full pensioner, up to 80% for a self-funded retiree. The logic the government uses is that these are costs everyone faces in life, so the person contributes more toward them. Whether or not your family agrees with the logic, knowing it helps you plan: an hour of cleaning costs your parent noticeably more, out of pocket, than an hour of nursing — which surprises almost everyone the first time they see a statement.
A practical way to use these categories: when you and your parent sit down with a provider to build the care plan, sort every wanted service into its category first. It turns a confusing price list into three small piles, and it shows you straight away where the budget does the heavy lifting (clinical) and where your parent's wallet does (everyday living). Families who do this sorting exercise make calmer decisions — and ask better questions — than families who shop hour by hour.
The 8 classifications and the quarterly budgets
Your parent's assessment places them in one of eight classifications, from Classification 1 (lowest needs) to Classification 8 (highest). Each classification carries a published quarterly budget — the figures below are the current amounts from the Department of Health, Disability and Ageing's funding schedule, and they are indexed every 1 July.
| Classification | Quarterly budget | Annual amount |
|---|---|---|
| 1 | $2,752.50 | $11,010.01 |
| 2 | $4,112.84 | $16,451.35 |
| 3 | $5,634.20 | $22,536.81 |
| 4 | $7,617.13 | $30,468.51 |
| 5 | $10,182.38 | $40,729.53 |
| 6 | $12,341.32 | $49,365.27 |
| 7 | $14,915.00 | $59,660.00 |
| 8 | $20,034.28 | $80,137.12 |
Three details hide inside those numbers, and all three matter. First, 10% of each quarterly budget is allocated to care management — the coordination work of planning, scheduling and reviewing care. It's already inside the published figures, not an extra fee on top. Second, the budget is genuinely quarterly. Your parent doesn't get a yearly pot to ration; they get a three-month budget, four times a year. Third, the carryover rule: if there's money left at the end of a quarter, they can carry over up to $1,000 or 10% of the budget — whichever is greater — into the next quarter. Anything beyond that doesn't roll forward. The old habit of letting funds quietly accumulate for a rainy day no longer works, and providers should be helping your family spend the budget on useful care each quarter rather than watching it evaporate.
What if the classification is wrong — too low for what life actually looks like now? Classifications aren't life sentences. If your parent's needs increase — a fall, a hospital stay, a carer who can no longer manage — they can be reassessed and moved to a higher classification with a larger budget. This is one of the most useful things a family can know: the system expects needs to change, and asking for a reassessment through My Aged Care is a normal, built-in step, not a complaint.
One more situation turns up often enough to name: sometimes funding is offered on an interim basis first — 60% of the classification amount — so critical services can start while the full allocation is processed. If your parent receives an offer that looks smaller than the table above, check whether it's an interim amount before you panic. The remaining funding follows when it becomes available; it isn't backdated, which is one more reason to get services started rather than waiting for a perfect arrangement.
What your family will actually pay
Your parent pays a contribution only toward services they actually receive, and only toward the non-clinical ones. Services Australia works the percentage out from their income and assets — pension status is the biggest driver — and the government pays the rest of each bill directly to the provider.
| Your parent's situation | Clinical supports | Independence supports | Everyday living supports |
|---|---|---|---|
| Full Age Pension | 0% | 5% | 17.5% |
| Part pension, or Commonwealth Seniors Health Card holder | 0% | Between 5% and 50%, tapered by income and assets | Between 17.5% and 80%, tapered by income and assets |
| Self-funded retiree without the Health Card | 0% | 50% | 80% |
Let's make that concrete, because percentages are slippery. Say your mum is a full pensioner and her provider charges $60 for an hour of cleaning (an everyday living service). Mum's contribution is 17.5% — $10.50 — and the government pays the remaining $49.50 from her budget arrangements. Now say the same hour is a nurse's visit instead: mum pays $0. Not a reduced amount — nothing. And if your dad is a self-funded retiree getting help with showering (independence), he pays 50% of that service's price. Same system, three very different wallets — which is why the only honest answer to "how much will it cost us?" is "it depends on the service type and your parent's assessment", and why anyone who quotes your family a single flat figure before an assessment is guessing.
Two protections are built in. There's a lifetime cap on contributions toward non-clinical care, so decades of support can't produce unlimited bills; and if money is genuinely tight, a fee reduction supplement exists for financial hardship — the government can cover some or all of a participant's contributions while they're in hardship. Neither is automatic or well advertised. If contributions are the thing standing between your parent and needed care, raise hardship with My Aged Care directly rather than quietly cancelling services.
One trap to avoid: the contribution percentages above assume Services Australia has your parent's income and assets information. If a participant doesn't provide it, they're treated as "means not disclosed" and charged the maximum rates. Every year, some families pay top rates for months simply because a form never got lodged. If your parent's statements show contributions that look like the maximum row of the table, the first question to ask is whether their assessment is actually on file.
And before any of this becomes real, use the Support at Home fee estimator on the My Aged Care website. It won't give a binding answer — only Services Australia's assessment does that — but it turns the table above into a rough monthly figure for your parent's actual situation, which is what most families are really asking for at the kitchen table.
Already had a Home Care Package? Read this first
If your parent already had a Home Care Package on 1 November 2025, they were moved to Support at Home automatically — no reapplication, no new assessment, no gap in services. Their funding continued at an equivalent level, and any unspent package funds came across with them.
The equivalent-funding promise has actual numbers behind it. Transitioned recipients keep funding matched to their old package level — roughly $11,272 a year for a former Level 1, $19,822 for Level 2, $43,149 for Level 3 and $65,416 for Level 4 (the precise quarterly figures are in the official schedule). Those amounts differ slightly from the new classifications table above, and that's deliberate: they mirror what the old package provided. If your parent is later reassessed into a higher Support at Home classification because their needs have grown, that's a separate step, initiated through My Aged Care.
What about the money they'd saved up in the old package — the unspent funds? Those were kept, and the rules for them are friendlier than the new quarterly rules: there's no carryover limit on old unspent funds, and they can be used for assistive technology and home modifications, or for extra services once a quarterly budget is fully spent. If your parent changes providers, the unspent funds transfer with them. Families sometimes assume this money vanished in the changeover. It didn't — ask the provider for the balance if it hasn't appeared on a statement.
Then there's the phrase your parent's letter may have used: the "no worse off" principle. It covers people who were receiving a Home Care Package, approved for one, or on the National Priority System waiting list on or before 12 September 2024. For them, contributions are protected: if they were assessed as paying no income-tested care fee under the old system (as at 31 October 2025), they will never be asked to pay contributions under Support at Home. If they were paying an income-tested fee, they'll pay the same or less. A lower lifetime cap applies to this grandfathered group too — $88,934.57 as at 20 September 2026, indexed twice a year. People approved for a package between 13 September 2024 and 31 October 2025 moved across as well, but under the standard new contribution rates — the no-worse-off protection doesn't apply to them. If you're unsure which group your parent falls into, their transition letters from My Aged Care say so, and their provider is required to apply the right schedule — it's worth one phone call to confirm, because the difference runs for the rest of their time in the program.
And if your parent was still waiting for a package when the change happened — on the old National Priority System queue — they moved into the Support at Home priority system automatically. When funding becomes available, they'll receive a classification equivalent to the package they were approved for, with no new assessment unless their needs have changed. The wait itself, sadly, didn't get shorter because the sign over the door changed.
How to apply for Support at Home: the 5 steps
Applying has five steps: contact My Aged Care, have an assessment at home, receive the decision and support plan, complete the income and assets assessment, then choose a provider and start services. Here's each step the way it actually unfolds for a family.
Step 1 — Contact My Aged Care (you can do this for your parent). Call 1800 200 422 or apply online at myagedcare.gov.au. Adult children do this part all the time; you'll need your parent's agreement to act for them, and their Medicare details help the conversation along. Be specific about what daily life now looks like — every task that's become hard, every fall, every thing a spouse is quietly covering for. This first conversation decides whether an assessment is arranged, and understated answers produce understated assessments. This is not the moment for "she's fine, really".
Step 2 — The assessment, at home. Under the Single Assessment System, an assessor visits your parent at home (you can be there — please be there) and works through their health, mobility, daily tasks, and what matters to them. Prepare like it's a job interview for help: a list of medications, the GP's details, and honest examples of what's difficult. "Dad can't get out of the bath without the towel rail" is evidence. "He's slowing down" is not. The assessor isn't judging your family — they're building the case for funding, and detail is the raw material.
Step 3 — The Notice of Decision and support plan. If your parent is approved, they'll receive a Notice of Decision letter and an individual support plan. This document matters more than any other in the process: it names their classification, their quarterly budget, and the list of services they're approved for — and, where relevant, approvals for short-term supports like assistive technology, home modifications, restorative care or end-of-life care. Read it against reality. If the approved services don't match what the assessor saw, that's fixable — but it's far easier to query early than after months of wrong services.
Step 4 — The income and assets assessment. Services Australia assesses your parent's income and assets to set their contribution percentages (the table in the payments section). Full pensioners' rates flow from their pension assessment; others may need to lodge details directly. Remember the trap: no information on file means maximum contributions. If your parent is a part-pensioner or self-funded, treat this step as part of the application, not an optional extra.
Step 5 — Choose a provider, agree prices, start. Your parent chooses their provider — the government doesn't assign one. Providers must publish their prices, and prices vary, so compare at least two or three for the services your parent will use most. Agree the care plan and the prices before services begin, in writing. Then services start, statements arrive showing what was delivered, what it cost, what your parent contributed and what's left in the budget. One honest warning: waits for funding allocation can be long, and an interim offer (60% of the classification) may come first. Long waits are exactly why Step 1 shouldn't wait for a crisis — the family that applies while Dad is "mostly fine" is the family whose funding exists the month he isn't.
Extra funding that sits outside the budget
Some of the most useful money in Support at Home doesn't come out of the quarterly budget at all. Three separate funding streams sit alongside it, and families who know about them get grab rails, recovery help and end-of-life support that other families pay for privately or go without.
Assistive technology and home modifications (the AT-HM scheme). Equipment and home changes are funded separately, in tiers based on assessed need: Low — $500, Medium — $2,000, High — $15,000 (or more in some cases), available for 12 months in most instances. This is the money for the shower chair, the raised toilet seat, the grab rails by the bath, the ramp at the front step — the exact fixes that prevent the fall that changes everything. Because it's separate, a $15,000 bathroom modification no longer cannibalises the money that pays for weekly care. If your parent's support plan includes an AT-HM approval, ask what tier they've been given and what's still unspent; our guides to grab bars for the bathroom and shower chairs for seniors can help you spend it well.
The Restorative Care Pathway. A short, intensive burst of support — funding of around $6,000 for up to 16 weeks — aimed at recovery and regaining independence after an illness, injury or hospital stay. Think physiotherapy, occupational therapy and strength work with a goal: not maintenance, but getting back to the garden, the shops, the stairs. If your parent is coming home from hospital weaker than they went in, ask whether they should be on this pathway rather than simply restarting their old services at their old level.
The End-of-Life Pathway. For someone with a prognosis of less than three months who wants to remain at home, this pathway provides funding of around $25,000 for 12 weeks (it can be accessed for up to 16 weeks) for the additional care that makes staying home possible. It's a hard paragraph to read and an important one to know exists, because decisions at that stage are made quickly, often in a hospital corridor. The funding is there so that "he wants to be at home" can be an actual plan, not just a wish.
What about the Commonwealth Home Support Programme?
If your parent gets lighter, entry-level help — a cleaner once a fortnight, meals, community transport — they may be under the Commonwealth Home Support Programme (CHSP), not a Home Care Package. CHSP was not replaced on 1 November 2025; it continues as its own program, and the government has indicated it will move into Support at Home at a later date. So if your parent's CHSP help simply carried on last November with no dramatic letter, nothing is wrong and nothing needs doing. The confusion only arises because both programs live under the My Aged Care umbrella — same front door, different rooms. When in doubt, one call to 1800 200 422 with your parent's details will tell you exactly which program they're in.
The family's action list: 5 things to do now
Everything above condenses into five actions. None of them costs anything, all of them prevent the common problems, and together they take an afternoon — print this page, and work through it with your parent or on the phone to their provider.
☐ Find the Notice of Decision. Confirm your parent's classification, quarterly budget and approved services match what the assessor saw.
☐ Check the contribution schedule on the latest statement. Does it match their pension status — and if it looks like the maximum row, is their income and assets assessment actually lodged with Services Australia?
☐ Ask for the unspent funds balance. Old package money didn't vanish — confirm the amount and what it can be spent on.
☐ Compare provider prices. Providers must publish them. Check what your parent is charged for their three most-used services against one or two other providers.
☐ Diarise a needs review. If anything has changed — a fall, a hospital stay, a carer struggling — request a reassessment through My Aged Care instead of silently making do.
Bring this list, the Notice of Decision and the latest statement to any meeting with a provider. It's also worth running our free Home Safety Score the next time you visit — the fixes it flags are often exactly what AT-HM funding can pay for.
Notice what isn't on the list: changing providers in a panic, cancelling everyday living services because the contribution percentage surprised you, or topping up privately before checking whether the budget or AT-HM could cover the same thing. The families who do well in this system aren't the ones who move fastest — they're the ones who read two documents (the Notice of Decision and the monthly statement) and make one phone call a quarter. That's genuinely most of the job. The rest of your energy belongs where it always did: on the visits, the shared meals, the ordinary time that no funding classification measures. Our caregiver checklist for ageing in place covers that side of the work — the home itself, room by room.
If your parent lives in a regional town
The rules are national — same classifications, same contribution table, same My Aged Care door — but the experience isn't. In a regional town the honest differences are supply and distance: fewer providers to choose from, workers travelling further, sometimes a wait for the right person rather than any person. Families out there can't change that, but three things genuinely help. First, apply early — regional queues reward the family that started before the crisis. Second, make the assessment count: with fewer services available, an accurate, detailed assessment (and a support plan that names the real approved services) matters even more, because it's the document every provider works from. Third, use the budget flexibly — transport to appointments, for example, is an independence support, and in a town where the specialist is 90 minutes away it's not a luxury line item, it's the service that makes every other service reachable. And if your parent's mobility is part of the picture, our elderly mobility scale calculator can help you describe their current level clearly in assessment conversations, and our guide to walkers for seniors covers the equipment side — equipment that AT-HM funding may well pay for.
Mistakes and red flags we've seen families hit
Being stoic at the assessment. The most expensive sentence in aged care is "we manage fine". Assessors can only fund the needs they hear described. If your parent performs independence for visitors, be the honest witness: describe the worst ordinary day, not the best one.
Never lodging the income and assets information. No information on file means maximum contributions — 50% and 80% — even for people who should be paying far less. If a statement looks wrong, check this first.
Signing with the first provider who calls. Providers must publish prices, and prices for the same service vary widely. Two comparison calls can save a budget hundreds of dollars a quarter. The pressure to "just start" is real, but a week of comparing beats a year of overpaying.
Letting the quarterly budget lapse. Under the old packages, unspent money waited for you. Now, beyond the carryover limit (the greater of $1,000 or 10%), it doesn't. If a quarter is ending with money unspent and needs unmet, that's a conversation to have with the provider immediately — more hours, the OT visit you've been postponing, the respite that lets the carer breathe.
Assuming the big repair must come out of the care budget. Ramps, rails and bathroom modifications belong to AT-HM, with tiers up to $15,000. Families who don't ask sometimes pay privately for exactly what the scheme exists to fund.
And the red flag above all: anyone who asks your family to pay for help applying, or who promises a particular classification or outcome. Applying through My Aged Care is free, eligibility is decided by assessment — not by charm, payment or pressure — and no honest service can guarantee a result. Walk away from anyone who says otherwise.
Who this guide is for — and who should skip it
This guide is for adult children and family carers helping a parent stay at home in Australia — whether you're reading a confusing transition letter, preparing for a first assessment, or checking whether Mum's new statements make sense. If that's you, welcome; the action list above is your starting point. You can safely skip it if your question is really about residential aged care (choosing a nursing home involves different funding and different decisions), or if your parent's finances are complex — property, trusts, a spouse still at home, a home to keep or sell. For that, a Services Australia Financial Information Service officer or an accredited aged care financial adviser is worth more than any guide, this one included. We'd rather tell you that than pretend a web page can carry that weight.
How we checked this guide
Every figure on this page was checked on 20 October 2026 against the Australian Government's own publications: the Department of Health, Disability and Ageing's Support at Home funding classifications (classification budgets, carryover, care management, AT-HM tiers and the short-term pathways) and its participant contributions page (contribution rates, the no worse off principle and the grandfathered lifetime cap), together with the My Aged Care program guide. Dollar amounts are indexed each year (budgets on 1 July; the grandfathered cap twice yearly), so treat the tables as current as of the date above and re-check them if you're reading this much later. One boundary we won't cross: we are not the government, a provider, or your parent's assessor. This guide explains the system in plain language; only My Aged Care and Services Australia can confirm what applies to your family's exact situation — 1800 200 422 is the number that settles arguments.
Frequently Asked Questions
- What is Support at Home in Australia?
- Support at Home is the Australian Government's program that funds help for older people living at home — things like nursing, personal care, cleaning, transport and equipment. It replaced Home Care Packages on 1 November 2025. You apply through My Aged Care (1800 200 422), have an assessment at home, and if approved you receive one of eight funding classifications with a quarterly budget to spend with a provider you choose.
- Do I need a new assessment if I already have a Home Care Package?
- No. Everyone with a Home Care Package was moved to Support at Home automatically on 1 November 2025, at an equivalent funding level, keeping their unspent funds. You only need a new assessment if your needs have changed and you want to be considered for a higher classification. Ask My Aged Care for a reassessment if daily life has become harder since the last one.
- How do I apply for Support at Home?
- Call My Aged Care on 1800 200 422 or apply online at myagedcare.gov.au. A family member can make the call with the older person's agreement. If they're eligible, an assessor visits them at home, and they then receive a Notice of Decision with their classification, quarterly budget and approved services. Services Australia separately assesses income and assets to set what they contribute toward non-clinical services.
- How much will my parent actually pay?
- Only toward services they receive, and never toward clinical care — nursing and allied health are fully government-funded. For other services the contribution depends on pension status: a full pensioner pays 5% of independence services and 17.5% of everyday living services, while a self-funded retiree without a Commonwealth Seniors Health Card pays 50% and 80%. Part pensioners fall in between. The fee estimator on the My Aged Care website gives a rough figure for your parent's situation.
- What is the difference between Support at Home and a Home Care Package?
- Home Care Packages had 4 levels, an annual package balance, and fees that could include a basic daily fee and an income-tested care fee. Support at Home has 8 classifications, a quarterly budget with limited carryover, no basic daily fee, and contributions charged as a set percentage of each non-clinical service. Equipment and home modifications are now funded separately through the AT-HM scheme instead of draining the care budget.
- What happens to unspent Home Care Package funds?
- They were kept. When your parent moved to Support at Home, their unspent package funds came with them. There is no carryover limit on those old funds, and they can be used for assistive technology and home modifications, or for extra services once a quarterly budget is fully spent. If your parent changes provider, the funds transfer too. Ask the provider for the balance if it isn't shown on a statement.
- How long does the assessment take?
- The assessment itself is a single visit at home, arranged after you apply. The full timeline — application, assessment, decision, and funding becoming available — varies, and can involve a wait, because funding is allocated as places open up. Some people start on interim funding of 60% of their classification while they wait for the full amount. Because of this, it is wise to apply early, before help is urgently needed.
- Can we choose our own provider — and change later?
- Yes. Your parent chooses their registered provider; the government doesn't assign one. Providers must publish their prices, so you can compare before deciding. If the fit is wrong — prices, reliability, or the actual workers — you can change providers, and your parent's funding and any old unspent funds move with them. Agree the new care plan and prices in writing before services restart.
- My dad lives in a regional town. Does Support at Home work the same out there?
- The program, classifications and contribution rules are national — the same in Cairns as in Carlton. What differs is local supply: fewer providers and longer travel distances can mean fewer choices and longer waits for a worker. The assessment still happens at home, and families often help by being present, keeping documents together, and comparing the providers who do service the area. If choice is very limited, say so to My Aged Care when you apply.
- What if Mum's needs get worse after she's classified?
- Ask for a reassessment. Classifications are not fixed for life: if your parent's needs increase — after a fall, a hospital stay or a decline — contact My Aged Care and request a reassessment for a higher classification and budget. The "no worse off" contribution protections still apply to people who had them, even after a reassessment to a higher classification.
- Does Support at Home replace the Commonwealth Home Support Programme (CHSP) too?
- Not yet. CHSP — the entry-level program for lighter help like cleaning, meals and community transport — was not replaced on 1 November 2025 and continues as its own program. The government has indicated it will move into Support at Home at a later date. If your parent's CHSP services simply continued, nothing is wrong and nothing needs doing.
- What happens to assessments and My Aged Care over Christmas?
- Your parent's place in the system is safe over the break, but the front door runs on holiday hours. The My Aged Care contact centre (1800 200 422) is closed on Sundays and national public holidays — that includes Christmas Day, Boxing Day and New Year's Day. The online application at myagedcare.gov.au works at any hour, and an application sent over Christmas is recorded exactly the same way as any other. Assessment visits are arranged for working days, so an application made in the holiday week will normally have its home visit booked for the new year. If your parent already has services running, those are arranged with their provider, not My Aged Care — ask the provider directly what happens on the public holidays.